Alert: We have received reports that fraudsters are spoofing Liberty First Credit Union's 855-501-4600 and 402-465-1000 phone numbers to make it appear they are calling from us. Never share your Online Banking credentials, verification codes, card numbers, PINs, or other sensitive information over an unsolicited phone call—if you're unsure whether a call is legitimate, hang up and contact us directly.

X

Blog

Financial Planning Checklist for New Lancaster County Residents

Key Takeaways / Summary:

  • Update your personal address with all financial institutions and service providers immediately after moving.
  • Transfer your everyday banking to a local credit union to enjoy low-cost services and higher earnings.
  • Establish direct deposit with your new employer to streamline your payday transfers.
  • Adjust your emergency savings budget to align with local living costs and homeownership needs.

Moving to a new community brings an exciting fresh start, but settling into Lancaster County also means taking care of important administrative tasks. 

Liberty First Credit Union can help new residents transition their finances smoothly so they can feel right at home. Following a simple financial checklist helps protect your money and sets you up for long-term success.

Update Your Address With Your Bank

One of the first steps after moving is updating your billing address with your current financial institutions. 

Outdated contact information can lead to missed paper statements, compromised security alerts, or delayed debit card replacements. Be sure to contact your accounts right away to update your profile.

Find a Local Credit Union Near You

Choosing a local credit union for new residents in Nebraska offers distinct advantages over national banks. 

We operate as a member-owned, not-for-profit financial cooperative where earnings are returned directly to our members through dividends and competitive loan rates. When you join, your share savings account balance of $5 represents your ownership share. 

Furthermore, our board of directors consists of volunteer members, meaning every member gets an equal voice.

Set Up Direct Deposit at Your New Job

If your move includes starting a new position, prioritize setting up direct deposit during employee onboarding. Having your paycheck deposited straight into your checking or savings account eliminates manual check deposits and gives you immediate access to your funds on payday. 

To set up direct deposit, simply request a direct deposit authorization form from your employer’s payroll or human resources department. You will need to provide your new account number along with the credit union’s routing number. 

Once processed, your salary will be transferred automatically each pay cycle.

Build a Local Emergency Fund

Relocating involves upfront expenses like security deposits, utility setup fees, or moving trucks. Rebuilding your emergency fund locally helps protect you from unexpected financial surprises. 

Maintaining these savings funds ensures that handling your finances after moving to Lancaster County remains smooth and worry-free.

Research Local Homebuying Options

Whether you are currently renting or planning to purchase a house, exploring regional real estate options early gives you a clearer financial picture. Working with local lenders allows you to secure competitive mortgage rates and personalized guidance tailored to the regional market.

Who Can Join Liberty First CU?

Our history began in 1935 as the Burlington Employees Cooperative Credit Association serving railroad workers. After expanding our charter over the decades, we adopted our current name in 2003. Today, if you live, work, worship, or attend school in Lancaster or Seward County, or are part of one of our partner groups, you are eligible to join us and enjoy the benefits of our cooperative model as well as your Family members.

Open Your Account in Minutes

Getting started is fast and straightforward. You can apply online or visit one of our physical locations to set up your membership with a simple $5 deposit. 

From there, you gain full access to our wide selection of affordable products and low-cost services.

Start Your Journey With Liberty First Credit Union

Moving to a new area is a major milestone, and having a trusted local financial partner makes all the difference. Learn more about our member benefits or contact us today to complete your new resident checklist.

Image credit: // Yuganov Konstantin // Shutterstock
Debit Card vs Credit Card: Which Should You Use for Everyday Spending?

Key Takeaways / Summary:

  • Use debit cards for strict daily budgeting and instant account deductions using your own cash.
  • Use credit cards for enhanced online fraud protection, building credit, and earning purchase rewards.
  • Combine both strategically to balance daily financial control with long-term security.

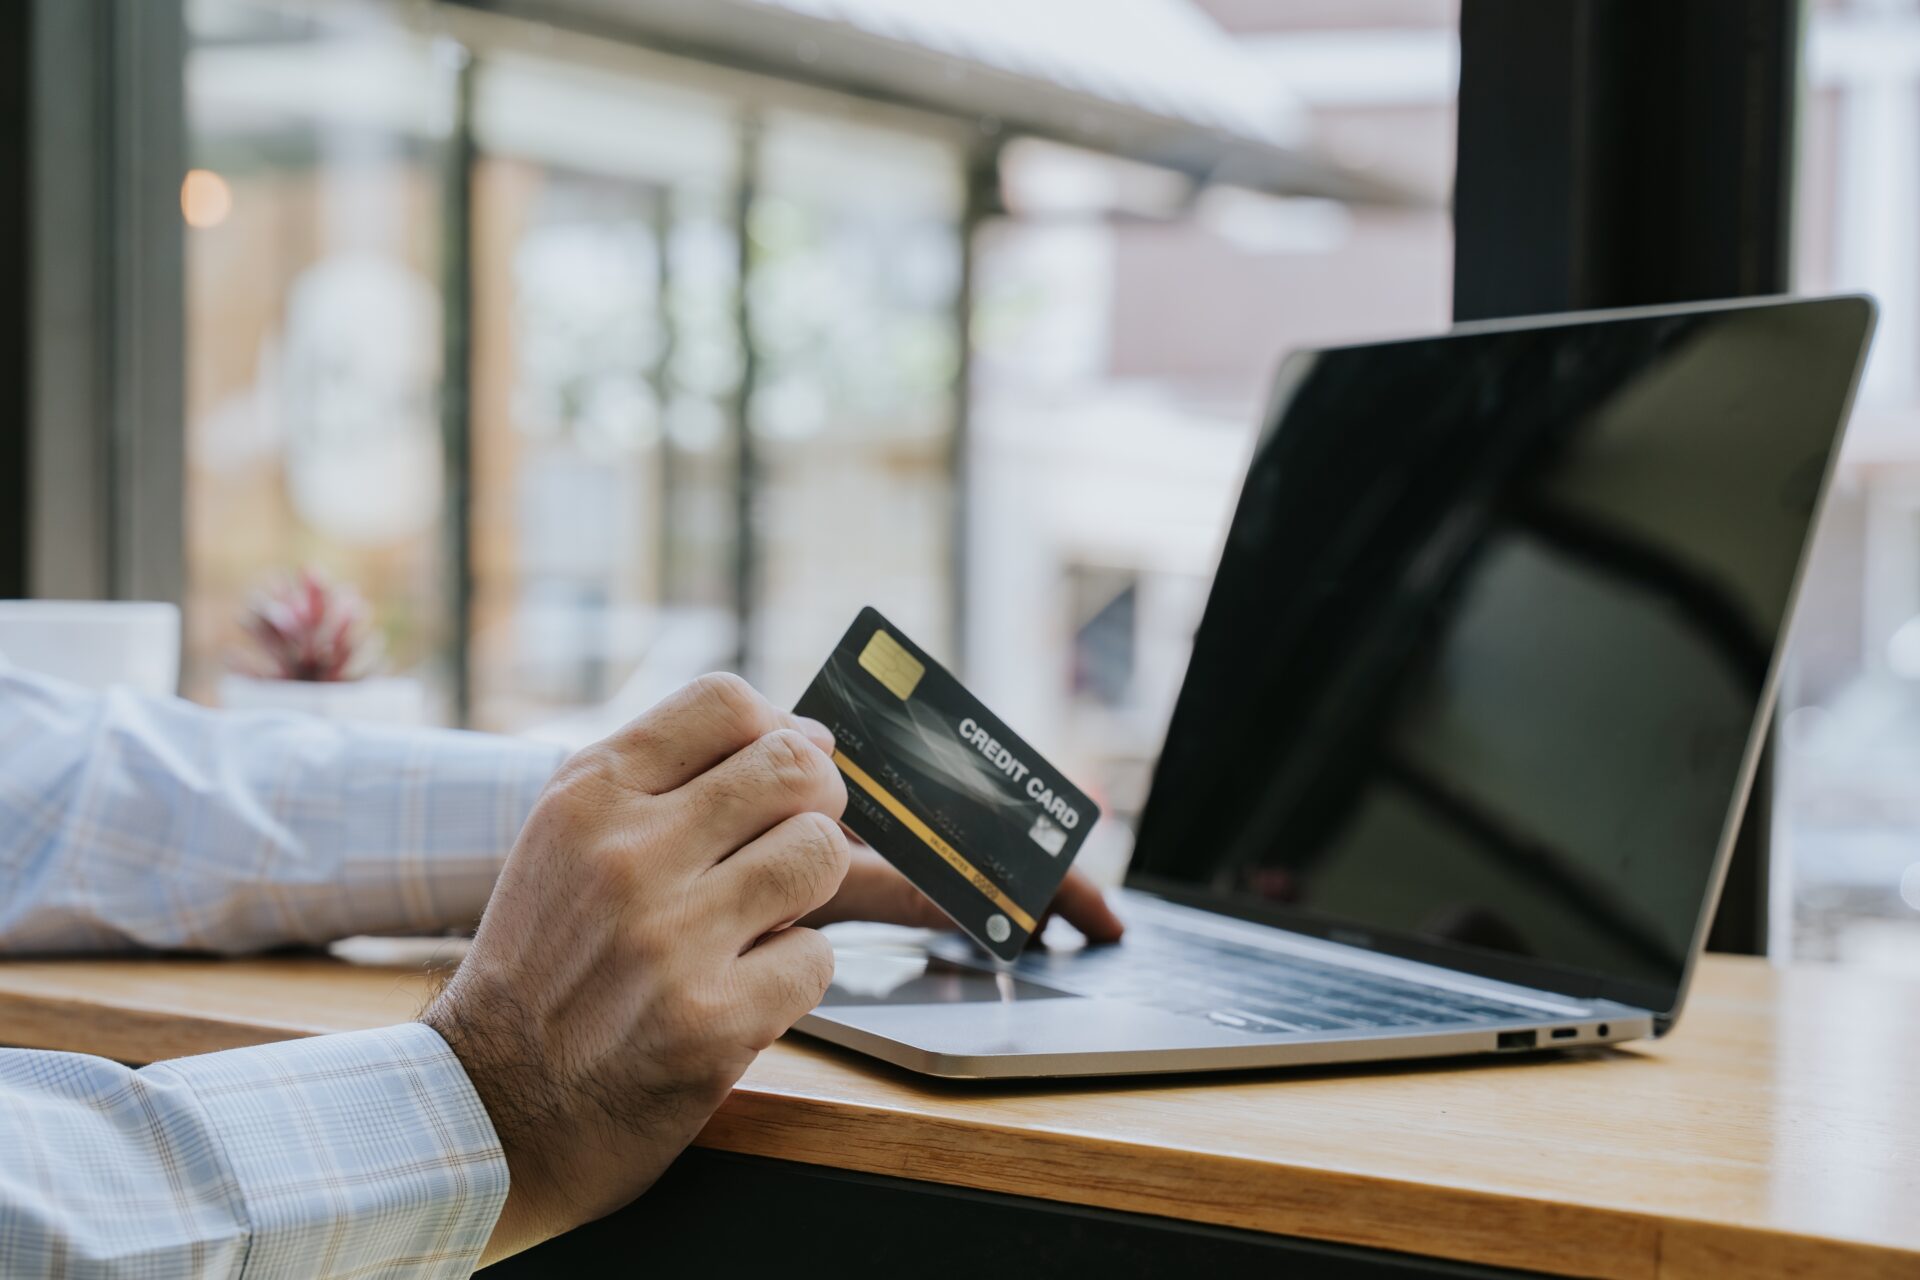
Choosing between a debit card and a credit card at checkout comes down to your personal financial goals. 

Liberty First Credit Union believes in empowering our member-owners with the tools and knowledge needed to spend smarter. Both payment methods offer great convenience, but understanding how they work helps you decide which card fits your daily routine in Nebraska.

How Debit Cards Work

A debit card connects directly to your checking account. 

When you make a purchase, funds are deducted straight from your available balance almost instantly. You are spending your own money, which keeps you from taking on debt or paying monthly interest fees. 

Debit cards also provide simple access to cash at local ATMs.

How Credit Cards Work

A credit card provides a revolving line of credit issued by a financial institution. Instead of pulling money directly from your bank account, the credit card issuer pays the merchant on your behalf. 

You receive a monthly statement detailing your total transactions. Paying your balance in full before the grace period ends allows you to borrow money interest-free while establishing a strong credit score.

Pros and Cons of Each

Debit cards excel at keeping budgets on track because you typically cannot spend more than what sits in your account. They help avoid monthly bills, debt accumulation, and finance charges. However, debit card usage typically offers limited help when trying to build a credit history.

Credit cards offer valuable benefits like purchase rewards, credit-building opportunities, and strong consumer protections. The trade-off is the potential risk of overspending, accruing interest, or facing late fees if the balance is not paid off completely each month.

Which Is Safer for Online Shopping?

Credit card purchases do not tap directly into your cash, therefore, fraudulent charges are easier to dispute without compromising your primary liquid funds.

Debit cards also feature fraud protection measures, but unauthorized transactions temporarily drain actual cash from your checking account while an investigation takes place. 

Credit cards generally offer superior protection for digital transactions. Using credit cards for online shopping provides an extra buffer between internet merchants and your personal bank account.

How to Use Both Wisely

Using a debit card for routine expenses like groceries or local coffee runs keeps daily spending bounded by your budget. 

Reserve credit cards for larger recurring bills, travel bookings, and web orders to maximize rewards and safety. Paying off your credit card balance immediately keeps your finances secure while generating valuable perks.

Liberty First’s Debit and Credit Card Options

We offer a Debit Card that provides direct account access, zero annual fee usage, access to over 30,000 fee-free CO-OP network ATMs, and enrollment in MyLFCU Rewards. 

For members looking to build credit or earn perks, our low-rate Mastercard Credit Card features no annual fees, no balance transfer fees, a 25-day grace period on purchases, and enrollment in MyLFCU Rewards. 

Both options include CardNav controls to monitor transactions right from your smartphone.

Start Spending Smarter with Liberty First Credit Union

Finding the right balance between debit and credit helps you reach your financial milestones with confidence. Ready to upgrade your wallet? Contact us today to learn more about our member benefits across Nebraska!

Image credit: // Waruenada // Shutterstock

What Happens to Your Credit Score When You Apply for a Loan?

Key Takeaways / Summary:

  • A loan application triggers a hard credit inquiry, which typically causes a small temporary score drop of less than five points.
  • Credit scoring models treat multiple inquiries for the same loan type within a fourteen to forty-five day window as a single event.
  • Prequalification checks and soft credit pulls allow consumers to review potential loan rates without impacting their credit scores.

A loan application represents a major financial milestone, whether you want to purchase a new car, remodel your home, or consolidate existing debt. Many borrowers worry about how credit checks might alter their credit rating during the process. 

Liberty First Credit Union helps members navigate borrowing decisions with clear information and personalized financial guidance. As a member-owned financial cooperative serving Lancaster County, Seward County, and communities across Nebraska, we empower our members to build strong financial futures. 

Once you understand what happens to your credit score when you apply for a loan, you can shop for financing without any unexpected surprises. 

Hard Inquiries vs Soft Inquiries Explained

Credit checks fall into two primary categories known as soft inquiries and hard inquiries. 

A soft inquiry occurs when you check your own credit score or when a lender pre-screens you for promotional offers. Soft inquiries do not affect your credit score in any way and remain invisible to potential lenders who review your report.

A hard inquiry occurs when you submit an official application for credit and authorize a lender to review your complete file. A loan application credit check in Lincoln, Omaha, and Seward, NE results in a hard inquiry on your report. 

Lenders review this detailed information to evaluate your payment history, existing debt obligations, and overall risk level before approving funds.

How Much Does Applying for a Loan Affect Your Score?

Many borrowers wonder, does applying for a loan hurt your credit in a lasting way? A single hard inquiry usually causes your score to drop by less than five points. Credit scoring models view new credit inquiries as a minor factor, accounting for only ten percent of your overall FICO score.

The minor score drop reflects a small temporary increase in statistical risk when a consumer seeks new credit lines. Responsible borrowers who maintain consistent on-time payment histories generally see their scores recover within a few short months.

How Long Does a Hard Inquiry Stay on Your Report?

A hard credit check remains listed on your credit report for up to two years. However, the actual impact on your score dissipates much faster than the entry itself. FICO scoring models only factor hard inquiries into your score calculation for the first twelve months. 

After twelve months pass, the inquiry no longer impacts your score calculation at all. Eventually, credit bureaus remove the inquiry record completely once the two-year mark arrives.

Tips to Protect Your Credit When Rate Shopping

Comparison shopping across multiple lenders helps you secure the lowest interest rates and best terms. Fortunately, credit scoring systems recognize that smart consumers shop around for auto, mortgage, or student loans.

Follow these practical steps to protect your hard inquiry credit score in Nebraska while rate shopping:

  • Complete all loan applications within a narrow fourteen-day window so scoring models group them as one single inquiry.
  • Avoid applying for multiple credit cards at the same time, because credit card applications do not qualify for rate shopping grouping rules.
  • Limit new credit applications in the months leading up to a major loan application like a home mortgage.

What Credit Score Do You Need for a Loan at Liberty First Credit Union?

Our credit union evaluates loan applications holistically rather than relying solely on a single credit score number. We review your complete financial picture, including your income stability, debt-to-income ratio, and history with our cooperative. 

While higher credit scores unlock our lowest available interest rates, we offer competitive financing options for members across various credit stages. Our local loan specialists work closely with you to find affordable monthly payment plans that fit your personal budget.

Check Your Rate Without Hurting Your Credit

Modern lending options allow you to explore loan possibilities before committing to a full application. You can speak with our lending team or request prequalification to preview estimated interest rates and loan terms without triggering a hard inquiry. Our member-focused team is here to walk you through every step of the borrowing process with full transparency. 

Please visit our contact page or visit a local branch today to discuss your upcoming financing needs.

Image credit: // Shutterstock // Pickadook

How to Set Up Online Banking Safely: A Guide for Nebraska Members

Key Takeaways / Summary:

  • Members can complete initial digital banking registration online using their account number and basic identification details.
  • Strong passphrases combined with multi-factor authentication protect account access from unauthorized log-ins across all devices.
  • Official mobile applications and automatic fraud alerts provide daily monitoring for secure account management throughout Nebraska.

Digital financial management offers unparalleled convenience, allowing you to check balances, transfer funds, and pay bills from the comfort of your home. Liberty First Credit Union strives to provide robust, user-friendly financial tools while keeping your personal information completely secure.

As a member-owned cooperative serving Lancaster County, Seward County, and neighbors across Nebraska, we prioritize your financial safety in every digital interaction. Clear knowledge on how to set up online banking safely allows you to enjoy modern financial tools while protecting your hard-earned savings.

Members looking for convenient online banking in Lincoln, NE can establish secure account access in just a few simple steps.

Setting Up Your Online Banking Account

Registration begins on our official website home page or through our official digital banking portal. You will need your member account number, social security number, date of birth, and a valid email address on file with us to verify your identity.

The system guides you through identity verification questions to ensure that only authorized account owners complete registration. This seamless credit union digital banking setup process establishes your digital user profile while connecting all eligible savings, checking, or loan accounts under a single secure portal.

Creating a Strong Password

Your account password serves as the primary barrier against unauthorized access to your funds. Choose a complex passphrase made of multiple random words, numbers, and symbols rather than simple birthdates or common family names. 

Avoid reusing passwords across different websites or financial institutions. You should update your credentials periodically and store them in an encrypted password manager rather than writing them down on paper.

Setting Up Two-Factor Authentication

Two-factor authentication adds a critical second layer of protection beyond your username and password. When you log in from an unfamiliar computer or smartphone, the system sends a unique verification code to your registered mobile phone number or email address. 

You must enter this temporary code before gaining account access. This additional step ensures that cybercriminals cannot access your portal even if they manage to discover your password.

How to Use the Mobile App

Our official mobile app transforms your smartphone into a secure financial management tool. You can access secure mobile banking in Nebraska wherever your daily routine takes you, whether you need to check a balance in Lincoln or deposit a check in Seward. 

Download our application exclusively from official platforms like the Apple App Store or Google Play Store. Enable biometric authentication options, such as fingerprint or facial recognition, to combine rapid login convenience with advanced security features.

Recognizing Phishing Attempts

Cybercriminals often use fraudulent emails, phone calls, or text messages that mimic legitimate financial institutions to steal personal information. Our credit union will never contact you unexpectedly to demand your full password, PIN, or verification codes. 

Be cautious of urgent messages claiming that your account is locked or demanding immediate financial action. Always verify sender web addresses and navigate directly to our official web page rather than clicking on links embedded in suspicious text messages.

What to Do If You Spot Suspicious Activity

Prompt action protects your funds if you notice an unfamiliar transaction or suspect your account credentials have been compromised. Review your account history regularly through our digital portal and set up automated push notifications for daily account activity. 

Change your login password immediately if you suspect unauthorized access. Contact our customer service team right away so we can freeze compromised cards, secure your digital profile, and guide you through resolution steps.

Contact Liberty First Credit Union to Learn More

Our dedicated team remains ready to help you navigate digital banking tools with complete confidence. Please visit our contact page or call your local branch to speak with a representative about securing your accounts today.us today to begin your homeownership journey.

Image credit: // Shutterstock // CL Stock

Nebraska First-Time Homebuyer Programs You Probably Don’t Know About

Key Takeaways / Summary:

  • First-time homebuyers in Nebraska can access state and regional assistance programs, such as NIFA, to secure crucial down payment and closing cost support.
  • To qualify for most of these financial assistance programs, applicants must not have owned a primary home in three years and must complete a certified homebuyer education class.
  • Liberty First Credit Union works directly with buyers to combine regional assistance programs with specialized credit union options and federal loans like FHA, USDA, and VA.

Purchasing your very first home in Nebraska is an exciting milestone, but navigating the financial requirements can feel overwhelming. Many buyers assume they need a large down payment to secure a property, but that is simply not true in 2026. 

Liberty First Credit Union is here to guide you through the process and help you uncover valuable state, federal, and local financial assistance options. As a member-owned, not-for-profit financial cooperative founded in 1935, we prioritize helping our members achieve homeownership without draining their life savings.

NIFA Homebuyer Assistance Programs

The Nebraska Investment Finance Authority, known as NIFA, offers incredible options to help make buying a home affordable. Their flagship Homebuyer Assistance Program provides a first and second mortgage combination. The second mortgage offers a percentage of the purchase price to cover down payments and closing costs. This second loan features a highly affordable interest rate over an extended term. Additionally, NIFA offers a new Build Home Program in 2026. 

Down Payment Assistance in Nebraska

Beyond statewide programs, regional opportunities exist to make purchasing a home even easier. These funds can help cover necessary upfront costs and may even support minor structural repairs to prevent unexpected maintenance expenses after move-in. Partnering with the right lenders helps you stack these opportunities to maximize your savings.

Federal Programs: FHA, USDA & VA Loans

Federal mortgage programs are also excellent pathways for first-time buyers. 

  • Federal Housing Administration loans require low down payments and feature flexible credit requirements.
  • United States Department of Agriculture loans are available if you are looking to purchase a home in a rural area.
  •  For active-duty military, veterans, and surviving spouses, Veterans Affairs loans provide exceptional benefits.

How to Qualify as a First-Time Buyer

To qualify for most of these programs, you must not have owned a primary residence in the past three years. State and local assistance programs usually require a minimum credit score, often starting at 640. 

You must also fall within specific household income and purchase price limits, which vary depending on your county. Completing a certified homebuyer education class is another common requirement that prepares you for successful homeownership.

How Liberty First Credit Union Works With These Programs

We walk alongside you at every step of your homebuying journey. We are a financial cooperative; our main goal is your financial well-being. Opening a simple share savings account with a balance of at least 5 dollars establishes your lifetime membership with us. 

We do not answer to outside shareholders. Instead, we return our earnings directly to our member-owners through competitive loan rates and low-cost services. Our team is fully equipped to help you combine credit union mortgage options with state and federal assistance programs.

Start Your Application Today

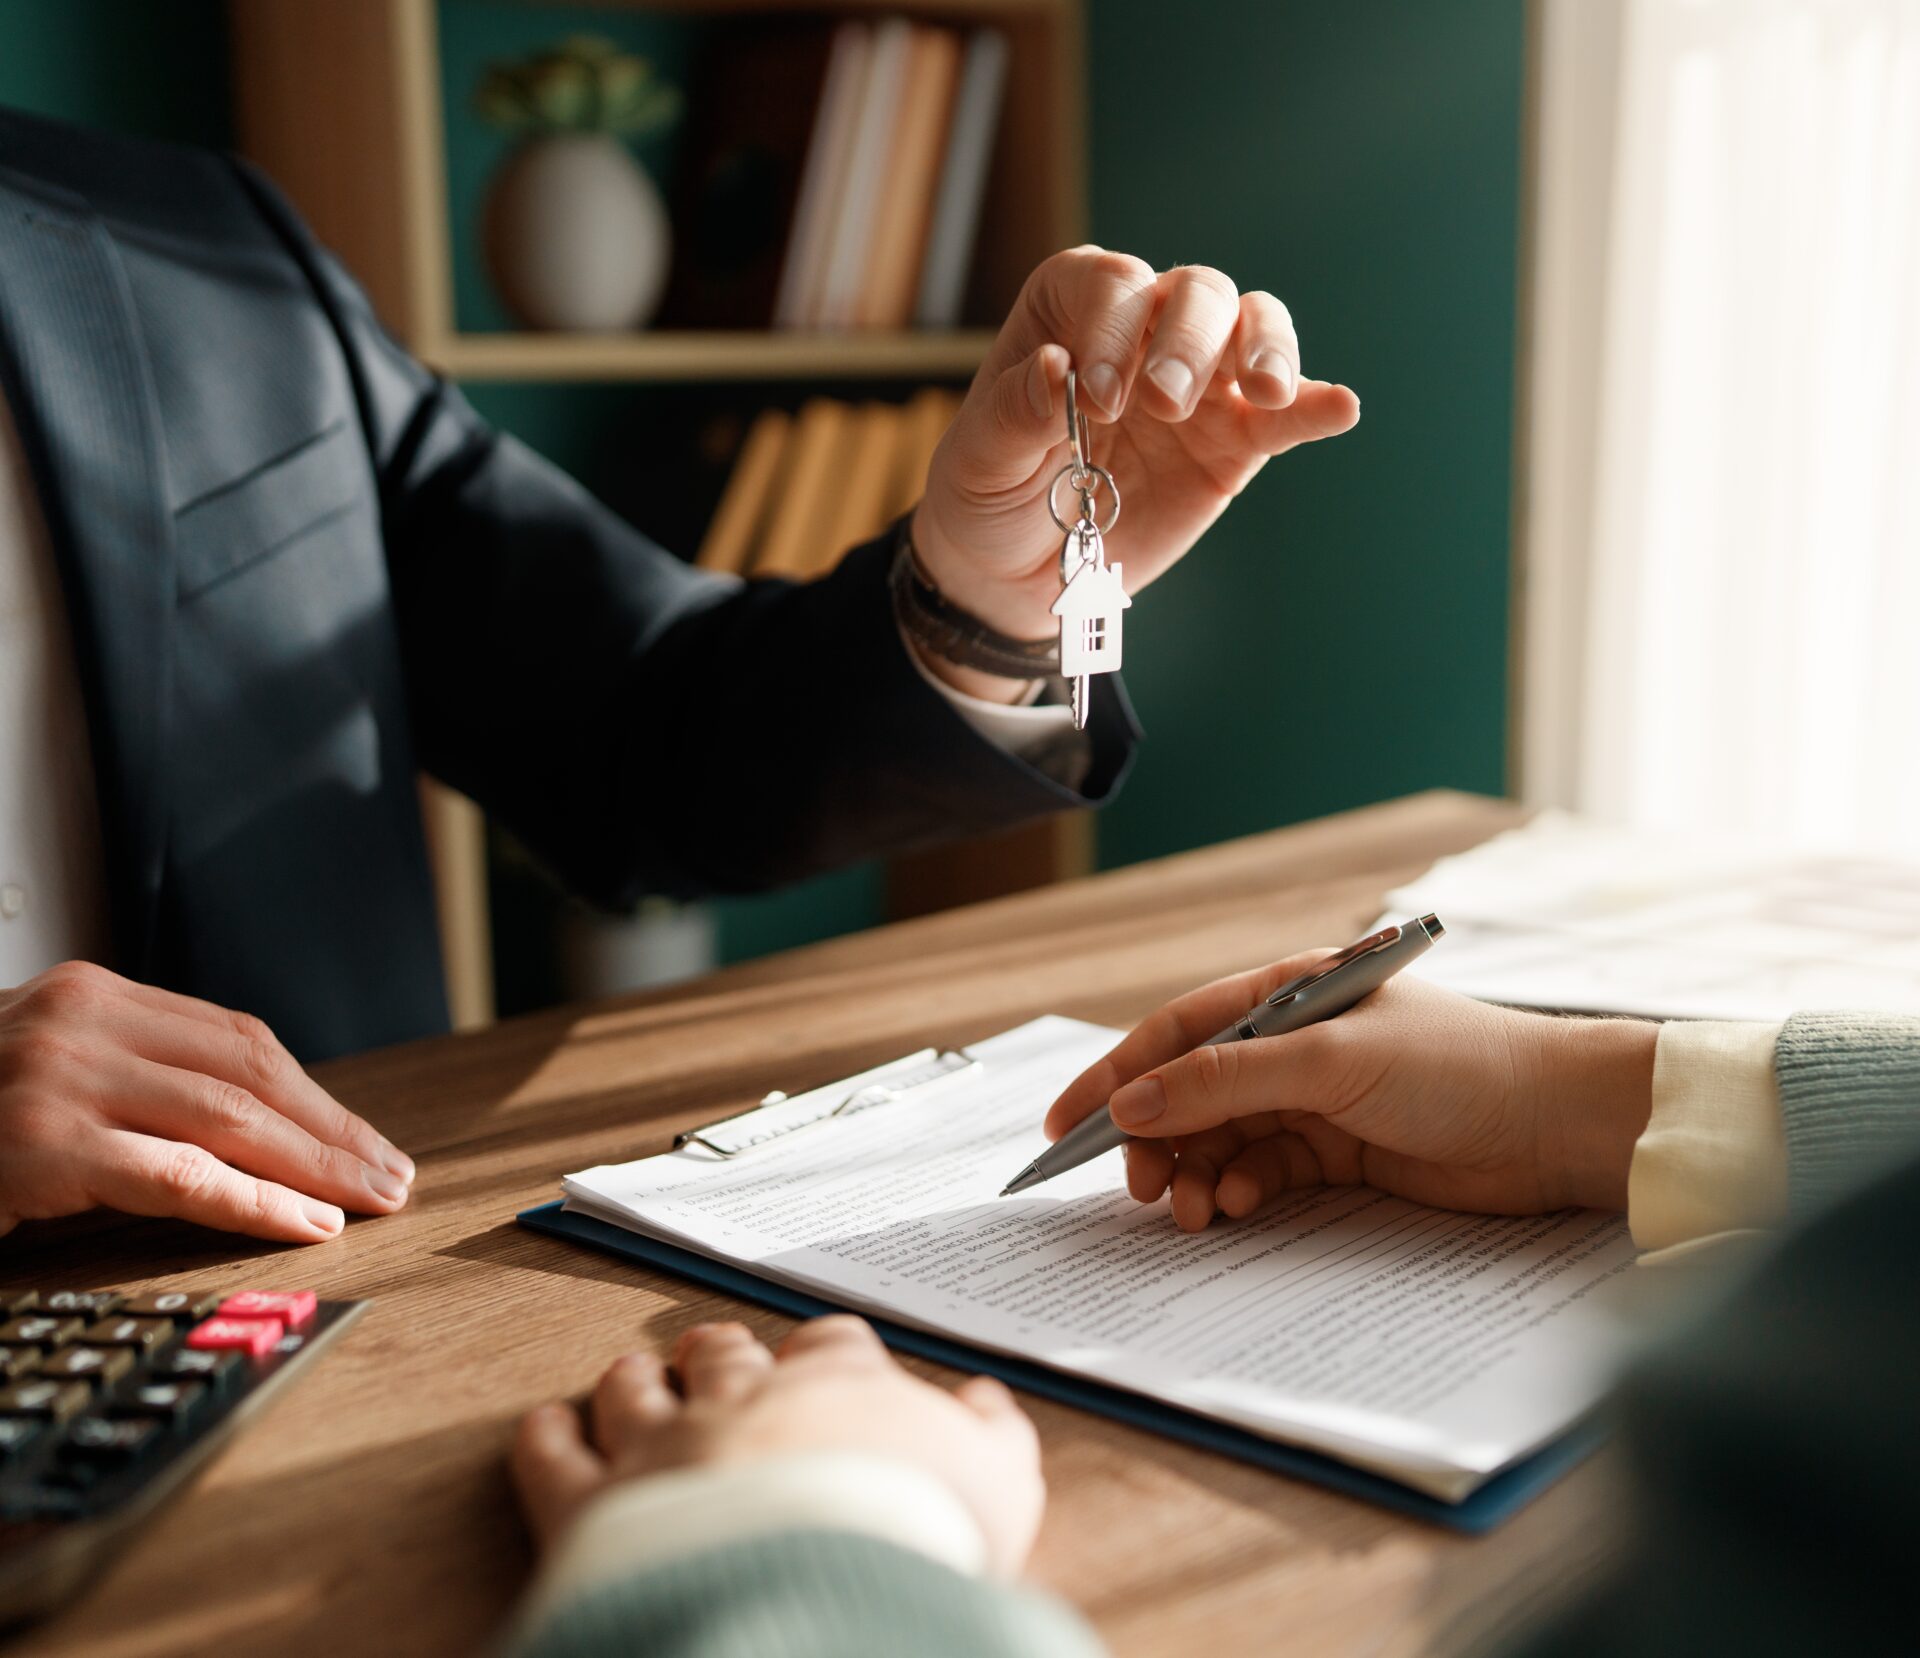
We are ready to help you open the door to your new home. If you are ready to discuss your options with a local mortgage expert, please contact us today to begin your homeownership journey.

Image credit: // Shutterstock // fizkes

How to Refinance Your Car Loan in Nebraska and Save Money

Key Takeaways / Summary:

  • Lower your interest rate: Reduce the overall cost of your vehicle by securing a more competitive rate.
  • Reduce your monthly payment: Adjust your loan term to fit your current monthly budget.
  • Switch to a local credit union: Benefit from member-first savings, lower fees, and personalized local service.

Finding yourself stuck with high monthly payments on your vehicle can put a serious strain on your budget. If you want to refinance a car loan, Nebraska options can help you keep more money in your pocket. 

Liberty First Credit Union offers straightforward pathways to lower your rate and restructure your debt. We operate as a member-owned cooperative, which means our earnings go right back to you in the form of better rates and lower fees. 

When Does It Make Sense to Refinance?

Refinancing makes sense if your credit score has improved since you first took out your auto loan. A higher credit score helps you qualify for a much lower interest rate. You might also consider this option if national interest rates have dropped since you bought your vehicle. Finally, if you need a lower car payment, Nebraska living expenses might make adjusting your monthly budget a top priority.

How Much Could You Save?

Even a small drop in your interest rate can add up to significant savings over the life of your loan. 

For example, lowering your rate by just one or two percent can save you hundreds of dollars in interest. Reducing your monthly payment also frees up cash for other important financial goals, which is why we offer competitive options for an auto loan refinance Lincoln, NE residents can trust.

What You Need to Refinance Your Car Loan

To get started, you will need to gather a few key pieces of information. Have your current loan statement, vehicle details like mileage and the Vehicle Identification Number, and proof of your monthly income ready. 

Step-by-Step: How to Refinance at Liberty First Credit Union

  1. Review your current auto loan details so you know your current rate, monthly payment, and remaining balance. 
  2. Check your credit score to ensure your report is accurate. 
  3. Submit your application for a refinance auto loan credit union option with us online or at one of our branches. 
  4. Once approved, we will help you pay off your old loan and set up your new, more affordable payment schedule.

Common Refinancing Mistakes to Avoid

One major mistake is extending your loan term too far out. While a longer term lowers your monthly payment, it can mean you pay more in total interest over the life of the loan. 

Another mistake is ignoring potential prepayment penalties from your current lender. Always read the terms of your existing loan before moving forward.

Apply to Refinance Today

Taking control of your auto debt is a smart financial move. If you live, work, worship, or attend school in Lancaster County or Seward County, you are eligible to join us and enjoy the benefits of our cooperative model. If you live in Nebraska or the surrounding States and are part of one of our member groups, you can join, too!

You can contact us today to speak with our team about starting your auto loan refinance journey.

Image credit: // Shutterstock // The KonG

Payday Loan Alternatives in Lincoln, NE

When you are facing an unexpected car repair or a medical bill that won’t wait, the promise of “fast cash” from a payday lender can be tempting. In Lincoln and across Nebraska, storefronts offering quick money with no credit check seem like a lifeline. However, these short-term solutions often lead to long-term financial struggles.

At Liberty First Credit Union, we believe in a “people helping people” philosophy. We want to help our neighbors in Nebraska understand the true cost of these loans and discover the ethical, affordable alternatives available right here at home.

Why Payday Loans Are Dangerous

Payday loans are designed to be repaid in a single lump sum, usually on your next payday. The danger lies in the “debt trap.” Because the repayment takes a massive chunk out of your next paycheck, many borrowers find they can’t cover their regular monthly expenses after paying back the loan. This forces them to take out another loan to get by, creating a cycle of debt that can last for months or even years.

What Are the Real Costs of a Payday Loan?

While a fee of $15 per $100 borrowed might not sound like much, it is deceptive. When you calculate the Annual Percentage Rate (APR), payday loans in Nebraska often exceed 400%.

Compare that to a credit card (usually 15-30% APR) or a personal loan from Liberty First Credit Union (significantly lower). When you choose a payday lender, you aren’t just borrowing money; you are paying a massive premium that strips wealth away from your family and hands it to a predatory corporation.

Better Alternatives for Fast Cash in Nebraska

If you live, work, or worship in Lancaster or Seward County, or belong to one of our partner groups, you have better options than a neon sign. Here are a few ways to get through a crisis without the triple-digit interest rates:

  1. Credit Union Small-Dollar Loans: Many credit unions offer “Payday Alternative Loans” specifically designed to help members through a pinch with fair terms and lower rates.
  2. Local Non-Profits: Organizations in Lincoln, such as Community Action Partnership or the Salvation Army, can sometimes assist with utility bills or emergency needs.
  3. Payment Extensions: Before borrowing, call your service provider. Many utility companies and landlords are willing to work out a one-time payment plan if you contact them before the due date.

How a Personal Loan From a Credit Union Compares

As a member-owned, not-for-profit financial cooperative, Liberty First Credit Union doesn’t answer to outside shareholders. Our “earnings” go back to you in the form of lower loan rates.

A personal loan from LFCU offers:

  • Predictable Monthly Payments: Instead of a single lump sum, you repay the loan in affordable installments.
  • Fair Interest Rates: Our rates are a fraction of what payday lenders charge.
  • Credit Building: Making on-time payments to a credit union helps improve your credit score, making it easier (and cheaper) to borrow money in the future.

Emergency Fund Tips to Avoid Future Shortfalls

The best way to beat the payday loan cycle is to build a buffer. Even if you can only save $5 or $10 a week, it adds up. At Liberty First, you can start a share savings account with just $5. This single share makes you an owner of the credit union.

Consider setting up an automatic transfer from your paycheck directly into a separate savings account. Having even $500 set aside can turn a major emergency into a minor inconvenience.

Apply for a Personal Loan at Liberty First Today

You don’t have to face financial hardship alone. If you are struggling to make ends meet, choose the ethical alternative that keeps more money in your pocket.

Apply for a Personal Loan at Liberty First Today or visit one of our branches in Lincoln or Seward to talk with a member advocate about your options. Let’s work together to achieve your financial goals.

How to Finance a Used Car in Nebraska: Credit Union vs Dealership

Buying a used car can be exciting, but the financing decision matters just as much as the vehicle you choose. Many Nebraska shoppers focus on the sticker price, mileage, and condition of the car, then wait until the last step to think about the loan. That can lead to rushed decisions at the dealership. Before you sign, it helps to compare dealership financing with a credit union auto loan to understand your options and shop with more confidence.

Dealer Financing: How It Really Works

Dealership financing can feel convenient because you choose the vehicle and discuss payment options in the same place. The dealer may work with multiple lenders to help you secure financing and then present loan options based on your credit, the vehicle, the loan term, and other factors.

Convenience is helpful, but it is still important to read the details. Monthly payment amount, interest rate, loan length, fees, add-ons, and total cost all matter. A lower monthly payment may look appealing, but a longer loan term could mean paying more over time. Before agreeing to dealership financing, ask questions and compare the offer with another option.

Credit Union Auto Loans: The Difference

A credit union auto loan gives you a chance to arrange financing before you start negotiating at the dealership. Liberty First Credit Union is a member-owned, not-for-profit financial cooperative that provides affordable financial services to its members. That member-focused structure can make a difference when you are looking for local guidance, competitive lending options, and a more personal experience.

With auto and personal loans through Liberty First Credit Union, Nebraska shoppers can explore financing options before visiting the lot. This can help you understand what may fit your budget and avoid making a rushed decision while sitting across from a salesperson.

Rate Comparison: Dealer vs Credit Union

When comparing a dealership loan with a credit union auto loan, look beyond the monthly payment. Compare the interest rate, loan term, fees, and total amount paid over the life of the loan. Even a small rate difference can affect what you pay over time, especially on a larger purchase.

A dealership may offer promotional financing in certain situations, but those offers may depend on credit qualifications, vehicle type, or loan terms. A credit union loan may give you a clearer starting point before you shop. The best choice depends on your financial situation, credit profile, and the details of each offer.

How to Get Pre-Approved Before You Shop

Getting pre-approved before shopping for a used car can make the buying process easier. Pre-approval gives you a better idea of your price range, helps you focus on vehicles that fit your budget, and gives you more confidence when comparing dealership offers.

Before applying, gather basic information such as income details, employment information, and an idea of the vehicle price range you are considering. You can also review Liberty First Credit Union’s pre-owned cars or connect with the consumer loan officers team for support.

What to Watch Out for at the Dealership

When reviewing dealership financing, take your time. Watch for extras that increase the total cost, such as optional protection plans, extended warranties, or added fees. These may be useful for some buyers, but they should be explained clearly before they are included in your loan.

Also, be careful when the conversation focuses only on the monthly payment. A payment may fit your budget but still have a longer term or a higher overall cost. Ask for the full loan details in writing so you can compare them with your credit union financing option.

Apply for a Used Car Loan at Liberty First Credit Union

If you are planning to finance a used car in Nebraska, Liberty First Credit Union can help you review your options before you visit the dealership. With local service and a member-focused approach, the team can help you understand the loan process and make a more informed decision.

Start by exploring Liberty First Credit Union’s auto loan options, or contact us to ask questions before you shop.

Image Credit: Summit Art Creations // Shutterstock

What Is a Money Market Account and Is It Right for You?

Saving money is easier when your account fits the way you manage your finances. Some people want a basic place to build an emergency fund, while others want an account that may offer stronger earning potential while still keeping funds accessible. That is where a money market account can be useful. If you are comparing savings options in Nebraska, Liberty First Credit Union can help you understand how a money market account works and whether it makes sense for your goals.

Money Market Account Definition

A money market account is a savings account designed to help your money grow while still giving you access to your funds. It often works well for people who want to save for short-term or medium-term goals, such as emergency expenses, home repairs, taxes, travel, or a future down payment.

Unlike everyday checking accounts, money market accounts are usually meant for saving rather than frequent spending. It gives you a dedicated place to keep funds separate from daily purchases, making it easier to stay organized and avoid dipping into savings too quickly.

How It Differs From a Regular Savings Account

A regular savings account is a strong starting point for many members, especially if you are building the habit of setting money aside. A money market account may be a good next step when your balance grows, and you want to compare account options.

The biggest difference often comes down to account structure, balance requirements, access, and earning potential. A standard savings account may be simpler for everyday savings, while a money market account may be better for larger balances that you do not need to move constantly. Liberty First Credit Union’s savings and MMA options can help members choose the account that fits their needs.

Money Market vs CD: Which Earns More?

A certificate of deposit, or CD, is another savings option that may offer competitive interest rates, but it usually requires you to keep your money in the account for a set term. That can be useful if you know you will not need the funds for a while.

A money market account may be a better fit if you want more flexibility. You can still set money aside, but you may have easier access to it than if you lock funds in a CD. The right choice depends on how soon you may need the money and how comfortable you are setting it aside for a fixed period.

Who Should Open a Money Market Account?

A money market account may be a good option for Nebraska members who already have some savings built up and want a separate place to keep it. It can be useful for:

• Emergency savings
• Future home expenses
• Vehicle repairs or replacement
• Tax savings
• Vacation funds
• Larger planned purchases

It may not be the best fit for someone who needs to spend from the account often or is just starting with a small savings balance. In that case, a basic savings account may be a better first step.

Current Money Market Rates at Liberty First

Rates can change, so it is important to review current information before opening an account. Liberty First Credit Union provides updated details through its deposit and loan rates page, giving members a clear place to compare available options.

How to Open Yours Today

Liberty First Credit Union is a member-owned, not-for-profit financial cooperative that helps members make confident financial decisions. If you are ready to compare savings options, explore the money market account details online or contact us to ask questions before opening your account.

Image Credit: Watchara Ritjan // Shutterstock

Best Mortgage Rates in Lincoln NE 2026

an image of a female banker giving a presentation to help describe the best mortgage rates lincoln ne from Liberty First Credit Union

Finding the perfect home in Lincoln is an exciting milestone, but navigating the financial landscape to secure the best mortgage rate can feel overwhelming. In 2026, the Nebraska housing market continues to evolve, making it more important than ever for buyers to understand what drives interest rates and how to find the best value.

At Liberty First Credit Union, we believe that informed members make the best financial decisions. As a member-owned cooperative, our “people helping people” philosophy means we are here to help you unlock the door to your new home with competitive rates and personalized service.

What Affects Your Mortgage Rate?

While national economic trends set the baseline, several personal factors influence the specific rate a lender offers you:

  • Credit Score: Generally, the higher your score, the lower your interest rate.
  • Down Payment: A larger down payment reduces the lender’s risk and can secure a better rate.
  • Loan Term: Whether you choose a 15-year or 30-year mortgage will impact your monthly payment and interest costs.
  • Property Type: Rates can vary slightly depending on whether the home is a primary residence, a secondary home, or an investment property.

Current Mortgage Rate Trends in Nebraska

In 2026, Nebraska’s market remains resilient. While national fluctuations occur, Lincoln and the surrounding Lancaster and Seward counties often see more stability than the coastal markets. Local demand for housing remains steady, and staying up to date on regional trends is essential for timing your purchase effectively.

Fixed vs. Adjustable-Rate Mortgages

Choosing the right loan structure is a critical step in your homebuying journey:

  • Fixed-Rate Mortgages: These offer stability with an interest rate that never changes over the life of the loan. This is ideal for buyers planning to stay in their Lincoln home for the long haul.
  • Adjustable-Rate Mortgages (ARMs): These typically offer a lower initial rate for a set period (like 5 or 7 years) before adjusting based on market conditions. This can be a strategic move if you plan to relocate or refinance in a few years.

How Credit Unions Offer Better Rates Than Banks

Why choose a credit union over a traditional big bank? The difference lies in our structure. Liberty First Credit Union is a not-for-profit financial cooperative. Unlike banks that must answer to outside shareholders, we answer only to our members.

Our earnings are returned to you in the form of lower loan rates, higher dividends on savings, and reduced fees. When you get a mortgage with us, you aren’t just a customer; you are a member-owner with a voice in how we operate.

Current Rates at Liberty First Credit Union

We pride ourselves on offering some of the most competitive mortgage rates in Lincoln and the surrounding communities. Because we are local, we understand the Nebraska market intimately. Whether you are a first-time homebuyer or looking to upgrade, we offer flexible terms tailored to your financial goals.

By keeping our overhead low and focusing on our “people helping people” mission, we ensure that your path to homeownership is as affordable as possible.

How to Apply for a Mortgage in Lincoln, NE

Getting started with Liberty First Credit Union is simple. If you live, work, worship, or attend school in Lancaster or Seward County, are related to someone who does, or belong to one of our partner groups, you are eligible for membership. A simple $5 deposit into a share savings account establishes your ownership in the credit union.

Our local mortgage experts are ready to guide you through the pre-approval process, helping you understand exactly how much home you can afford before you start your search.

Ready to find your home in Lincoln? Contact us at Liberty First Credit Union today to discuss our current rates and start your application. Let us help you make your dream of homeownership a reality.

Image Credit: Fahng_S // Shutterstock

Top
Liberty First Credit Union
Privacy Overview

This website uses cookies so that we can provide you with the best user experience possible. Cookie information is stored in your browser and performs functions such as recognising you when you return to our website and helping our team to understand which sections of the website you find most interesting and useful.